 Marianne Skorupski
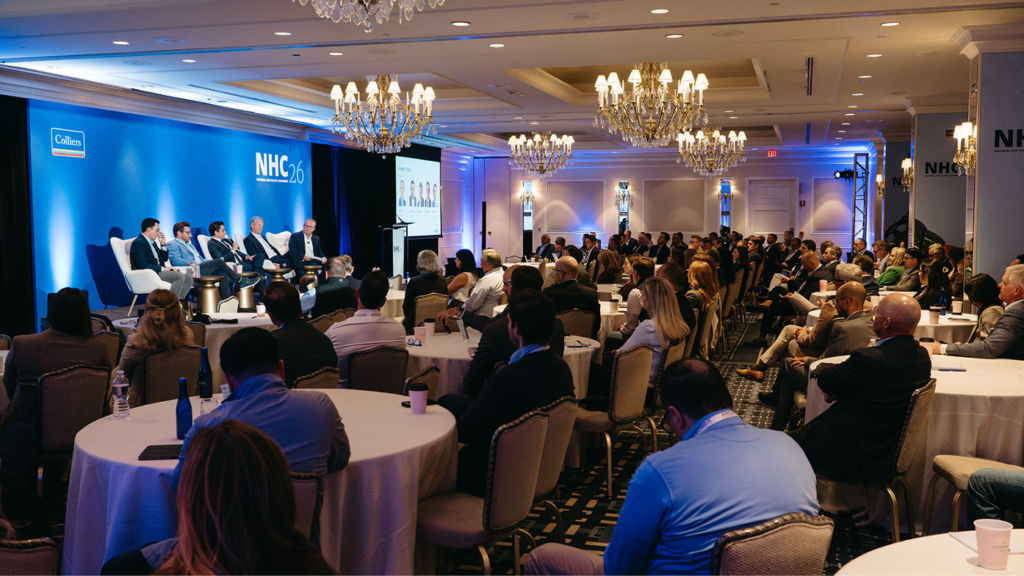
Colliers hosted its National Healthcare Conference in Boston, Massachusetts, October 7-9, 2026. The conference brought together healthcare providers, investors, developers, and industry experts to explore the forces shaping healthcare delivery, real estate strategy, investment activity, and market performance.
The key takeaways shared below capture the most important trends discussed throughout the event, including the continued shift toward outpatient care, evolving capital markets, workforce challenges, demographic tailwinds, and the growing strategic role of healthcare real estate in expanding patient access and supporting long-term organizational growth.
Healthcare Industry
- Outpatient growth remains the top priority, as health systems become more strategic real estate operators, pursuing joint ventures, land banking, and mixed-use development opportunities to drive growth and generate new revenue streams.
- Regulatory and financial pressures are mounting, including CON reform, heightened scrutiny of healthcare transactions, and upcoming Medicaid funding cuts that could significantly affect rural and safety-net hospitals.
- Hospitals continue to invest heavily in campuses, particularly through destination-campus strategies, new patient towers, children’s hospitals, and modernization projects in high-growth markets.
- Capital is becoming more creative and diversified, with large philanthropic donations, strategic partnerships, and joint ventures playing an increasingly significant role in funding healthcare real estate development.
- Healthcare finances have largely returned to pre-pandemic levels, but underlying structural challenges remain, including reimbursement pressures and the need for ongoing portfolio rationalization.
Government Impact
- Government reimbursement is expected to face sustained pressure as federal efforts to address rising debt levels drive attempts to reduce healthcare spending.
- Medicaid funding cuts and stricter eligibility requirements could significantly affect providers, particularly safety-net, urban, and rural hospitals that rely heavily on government reimbursement.
- The loss of Affordable Care Act marketplace subsidies is increasing the uninsured population, creating financial challenges for hospitals, and reducing elective procedure volumes.
- Healthcare organizations must balance cost containment with growth opportunities, as reimbursement headwinds are accelerating the need for operational efficiency, strategic investments, and careful market positioning.
Providers
- Patient access is driving real estate decisions, with health systems expanding care closer to where patients live, work, and shop.
- Outpatient and ambulatory facilities remain the primary growth focus, thereby reducing reliance on traditional hospital campuses.
- Capital constraints are increasing pressure to improve efficiency, prompting organizations to optimize existing space and pursue lower-cost expansion opportunities.
- Site selection extends beyond demographics, with accessibility, parking, visibility, and provider convenience playing critical roles.
- Healthcare providers are actively re-evaluating their portfolios to modernize, consolidate, repurpose, and optimize assets to support evolving care delivery models.
Investors
- Healthcare real estate remains highly attractive to investors, as ample equity and debt capital compete for a limited supply of quality assets.
- Transaction activity is expected to continue despite rate volatility, as buyers and sellers increasingly adapt to a higher-for-longer interest-rate environment.
- Development is becoming a key growth strategy as investors pursue new outpatient facilities, inpatient rehab hospitals, freestanding EDs, and other healthcare property types to overcome supply constraints.
- Alternative healthcare asset classes are attracting institutional interest, particularly inpatient rehabilitation facilities, freestanding emergency departments, and other higher-acuity outpatient facilities.
- The shift of care to outpatient settings continues to create investment opportunities, supported by regulatory changes, the expansion of ambulatory care delivery, and growing demand for modern healthcare facilities.
Economy
- The U.S. economy is increasingly bifurcated, with higher-income households driving spending while lower-income consumers face mounting financial strain.
- Interest rates are likely to remain elevated because inflation remains above target and markets anticipate further Federal Reserve rate increases.
- Healthcare faces a significant labor shortage, driven by an aging workforce, lower labor participation, reduced immigration, and growing shortages of physicians and nurses.
- Demographics remain a powerful tailwind for healthcare demand, as the 65+ population is expected to grow substantially over the next decade.
- Healthcare real estate strategy must prioritize workforce availability alongside demographic factors, as strong demand alone will not support growth if providers cannot adequately staff facilities.
Across every discussion, one message was clear: healthcare real estate is no longer simply a support function. As providers pursue growth, improve access, and adapt to financial and workforce challenges, real estate strategy will play an increasingly important role in shaping organizational performance and patient outcomes.
 Ron Goodin
 Shawn Janus