- Net lease acquisition volume increased approximately 60% year over year in the second quarter and nearly 90% versus Q2 2024.
- Same-property NOI growth expectations increased to roughly 0.8% annually as projected credit losses declined.
- Public net lease REITs continue to trade at an average 12% premium to gross asset value, supporting external growth.
- Average investment spreads compressed to roughly 40 basis points in Q2 2026.
Transaction activity remains one of the brightest spots within commercial real estate. Net lease REITs continue to benefit from healthy tenant fundamentals, robust acquisition activity, and favorable access to capital. Second-quarter acquisition volume rose roughly 60% year over year, while stronger tenant health reduced expected credit losses and lifted same-property NOI growth forecasts. However, acquisition cap rates compressed as implied cap rates increased, narrowing investment spreads. The sector still offers attractive growth opportunities, although narrower spreads make future growth more sensitive to acquisition pricing.
Public net lease REITs trade at an average 12% premium to gross asset value, giving most companies a favorable cost-of-capital position and supporting accretive external growth. Combined with robust transaction markets, that advantage has enabled REITs to acquire assets at an elevated pace, driving projected annual asset-base growth of roughly 10% from 2026 through 2028.
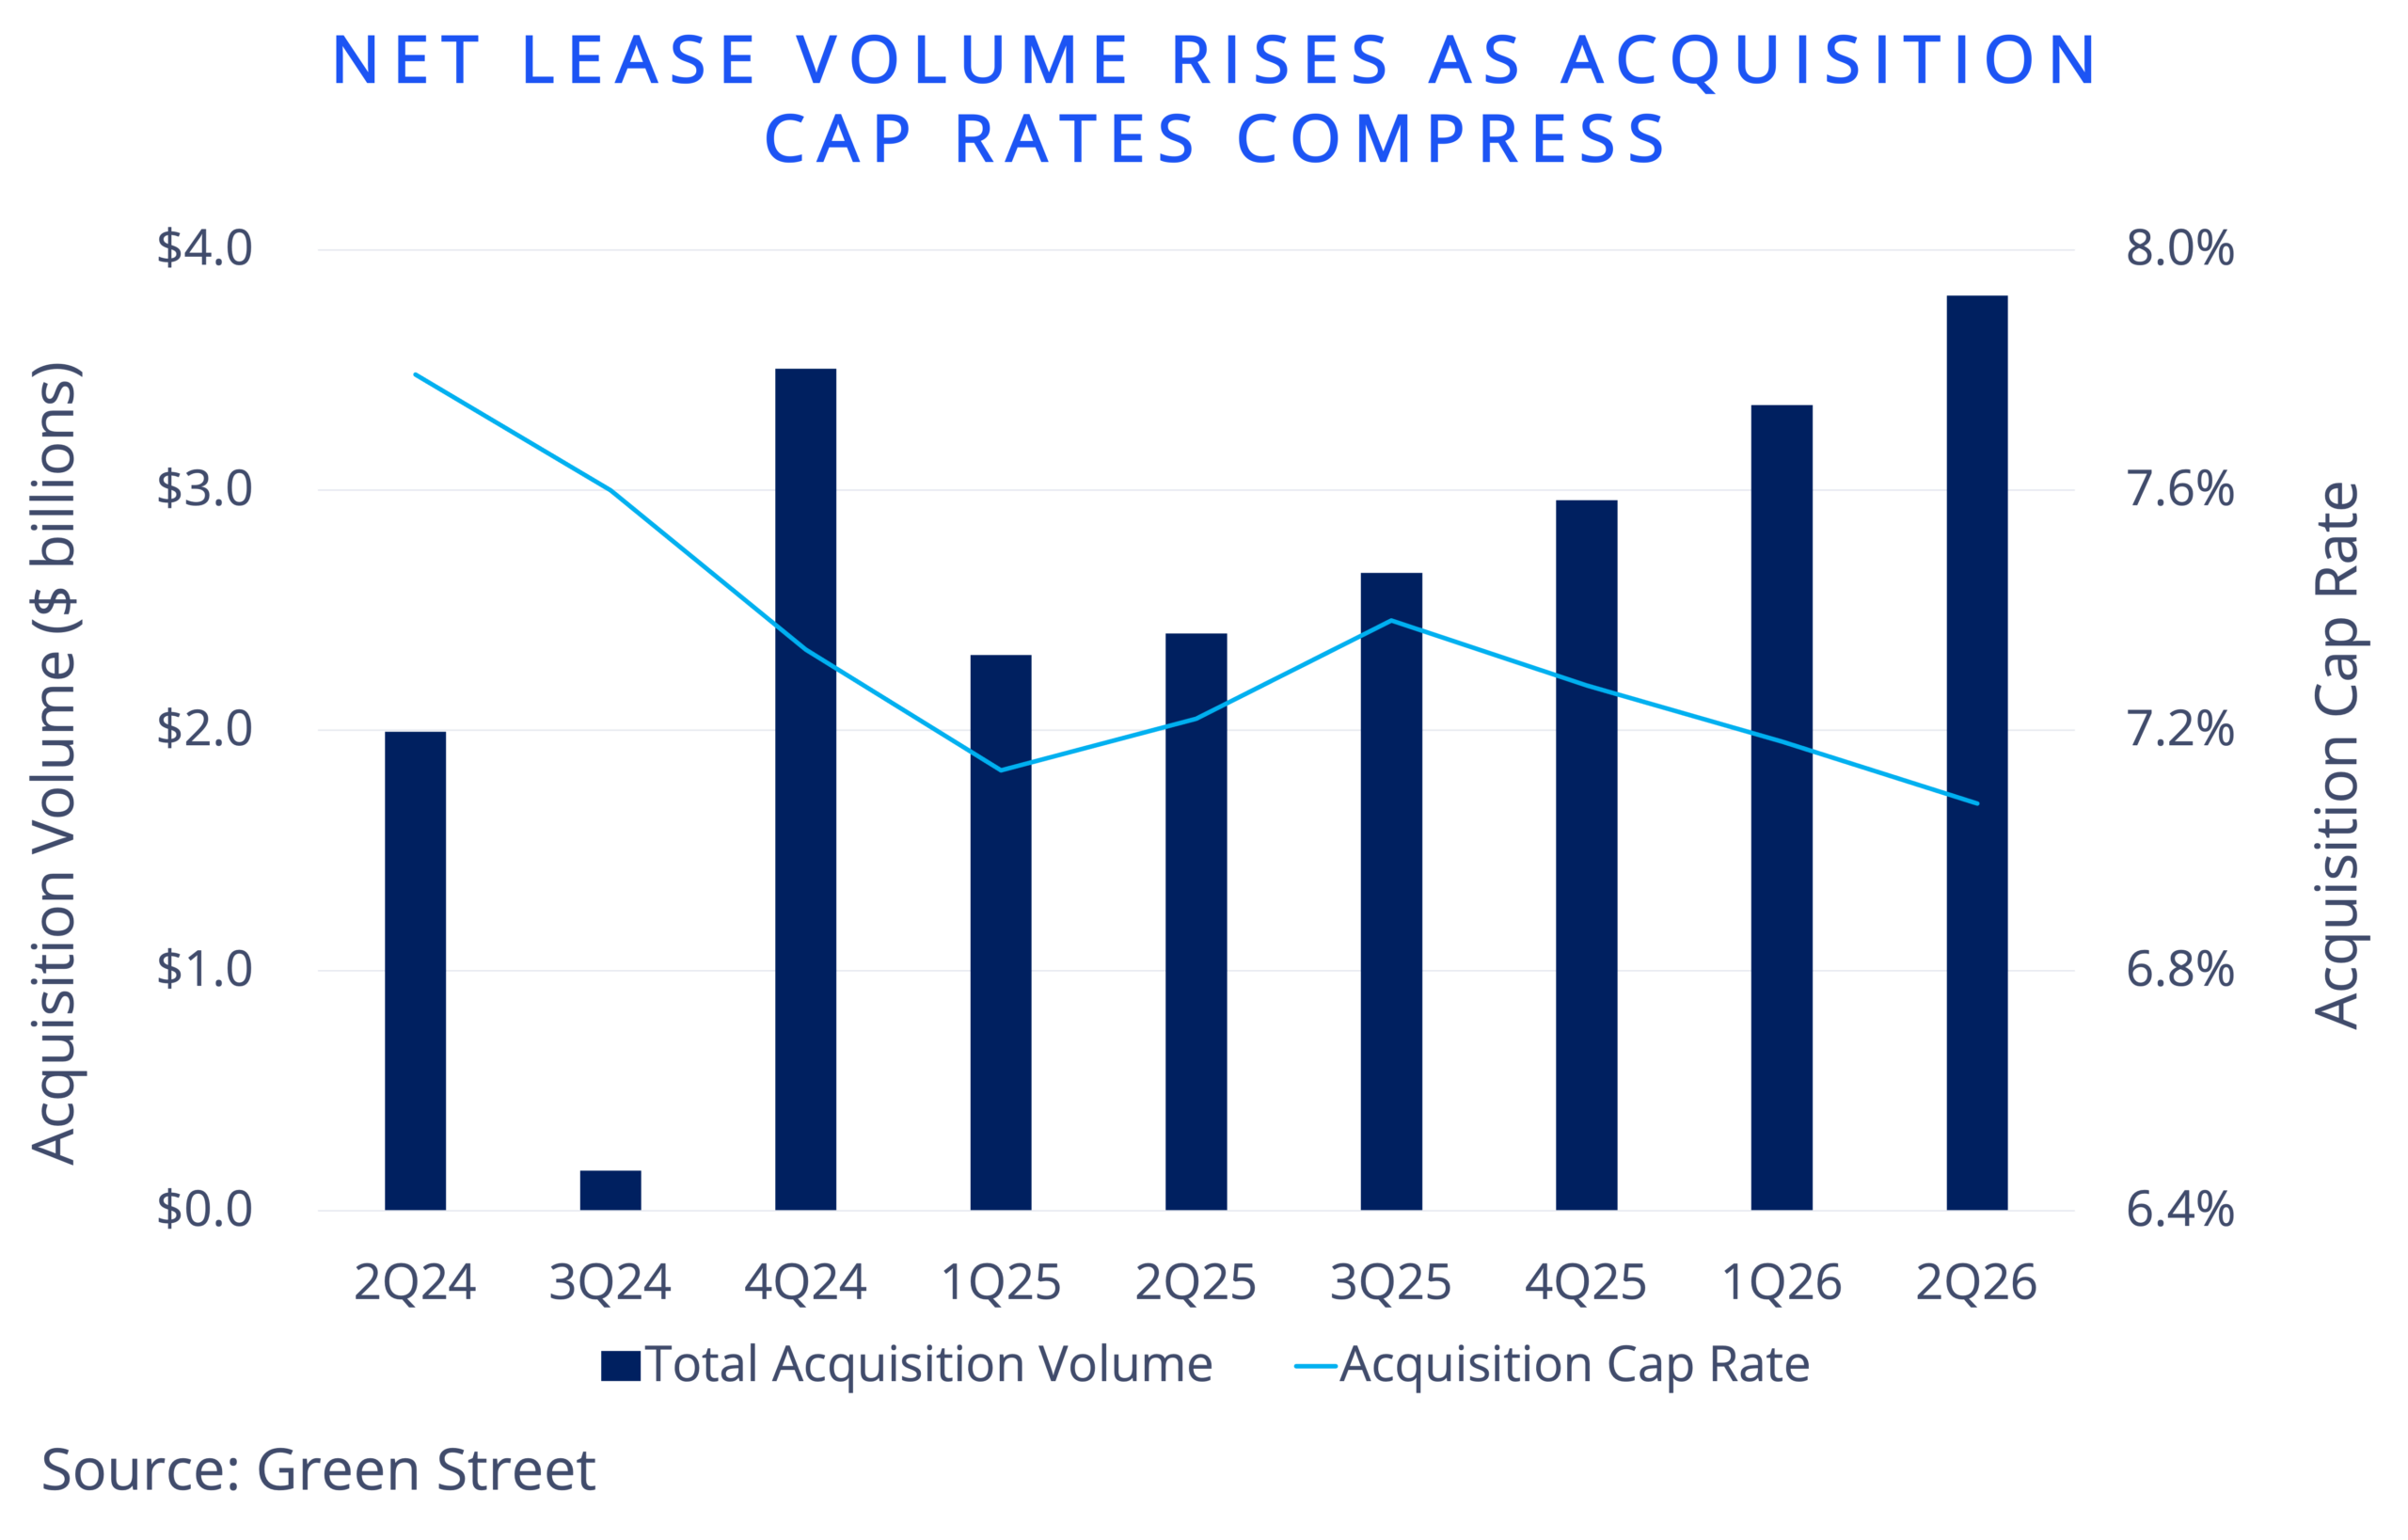
Property fundamentals have also improved. Expected credit losses have declined to roughly 90 basis points annually, helping lift projected same-property NOI growth to approximately 0.8% per year through 2030. REITs with greater CPI-linked lease exposure and more favorable contractual rent escalators are positioned for better internal growth.
The primary challenge is spread compression: average acquisition cap rates declined to 7.1%, while implied cap rates increased to 6.7%, reducing the average investment spread to roughly 40 basis points. Even so, most public REITs retain a cost-of-capital advantage. Green Street expects easing transaction urgency and competition during the second half of the year to support higher acquisition cap rates and potentially improve spreads.
 Steig Seaward
Net lease acquisition volume climbed roughly 60% year over year, even as investment spreads compressed to roughly 40 basis points.
Information Provided Herein Has Been Sourced From Green Street Advisors, LLC. This document and the information provided herein has been prepared by Colliers for advertising and general information only. Colliers makes no guarantees, representations or warranties of any kind, expressed or implied, regarding the information including, but not limited to, warranties of content, accuracy and reliability. Any interested party should undertake their own inquiries as to the accuracy of the information. Colliers excludes unequivocally all inferred or implied terms, conditions and warranties arising out of this document and excludes all liability for loss and damages arising therefrom. This publication is the copyrighted property of Colliers and/or its licensor(s). ©2026.
 Rachael Rothman