 Nicole Larson
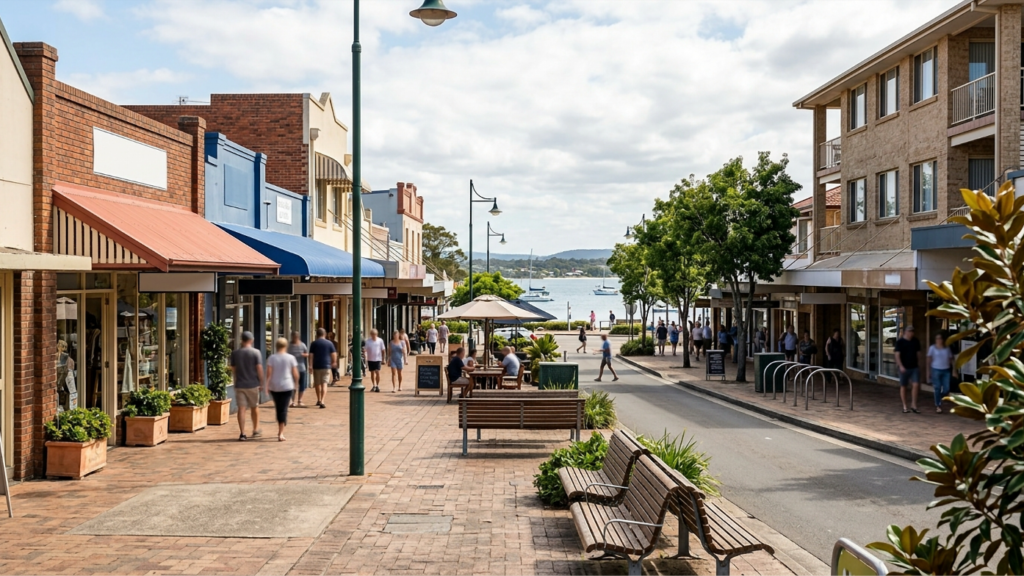
Retail fundamentals strengthened during the third quarter of 2026, supported by accelerating tenant demand, limited new supply, and continued consumer engagement with physical stores. Despite persistent inflationary pressures and economic uncertainty, retailers continued to expand and backfill available space, reinforcing the sector’s resilience as shoppers prioritized value, convenience, and experiences.
National retail vacancy declined 10 basis points to 4.3% during the quarter, remaining near historic lows. Shopping center vacancy improved to 5.4%, down 10 basis points from Q2, while mall vacancy declined 30 basis points to 8.2%. Limited new construction and continued demand for well-located retail space helped support occupancy across property types, particularly within smaller retail formats.
Retail leasing activity totaled 38.4 million square feet in Q3, while net absorption reached 10.5 million square feet, the highest quarterly absorption total since 2023. General retail led demand with 5.4 million square feet absorbed, followed by shopping centers (3.0 million SF) and malls (1.9 million SF). General retail encompasses freestanding properties and mixed-use retail, including restaurants, grocery stores, pharmacies, and standalone big-box retailers. Positive absorption across all three property types highlights continued retailer expansion and the backfilling of available space.
Retail development remained constrained, with 58.1 million square feet under construction and 7.6 million square feet delivered during the quarter. Elevated construction and financing costs continue to limit speculative projects, keeping new supply concentrated in select markets and development formats. Dallas-Fort Worth maintained the nation’s largest construction pipeline at 7.2 million square feet, followed by Houston (5.1 million SF) and Austin (3.2 million SF), underscoring Texas’ continued dominance in retail development.
Consumer visitation remained resilient throughout Q3, with national retail foot traffic increasing an indicative average of 1.9% year-over-year, compared with 2.2% in Q2. Value-oriented retailers continued attracting shoppers, while apparel emerged as a standout performer. Department store visitation increased 8.5% in July, 5.3% in August, and 11.7% in September, while clothing retailers posted gains of 6.3%, 3.6%, and 7.2%, respectively. Experiential and specialty retail also maintained momentum, with hobbies, gifts, and crafts recording visitation growth of nearly 20% or more each month, while fitness concepts consistently outperformed.
Notably, visitation to theaters and music venues surged 58.3% in August, reflecting a sharp rebound in entertainment traffic and suggesting strong consumer interest in out-of-home experiences during the summer season. Despite continued pressure on household budgets and elevated living costs, consumers remained engaged with physical retail throughout the quarter, prioritizing value, convenience, and experiences while becoming increasingly selective with their discretionary spending.
Average asking rents reached $26.20 per square foot, up 0.7% quarter over quarter. While headline rent growth continues to normalize, limited availability, improving retailer productivity, and favorable leasing economics continue to support pricing. Looking ahead, constrained development and healthy tenant demand should reinforce retail fundamentals, positioning the sector for continued stability and measured rent growth through the remainder of 2026.
Download the U.S. Retail Market Statistics infographic here: 3Q26 Retail Stats

 Anjee Solanki
 Haley Boatright

 Marianne Skorupski