Pricing trends and transaction activity continue to shape how the market evolves. At Colliers, we analyze these signals to interpret shifts across U.S. commercial real estate. Here’s what the latest MSCI data reveals.
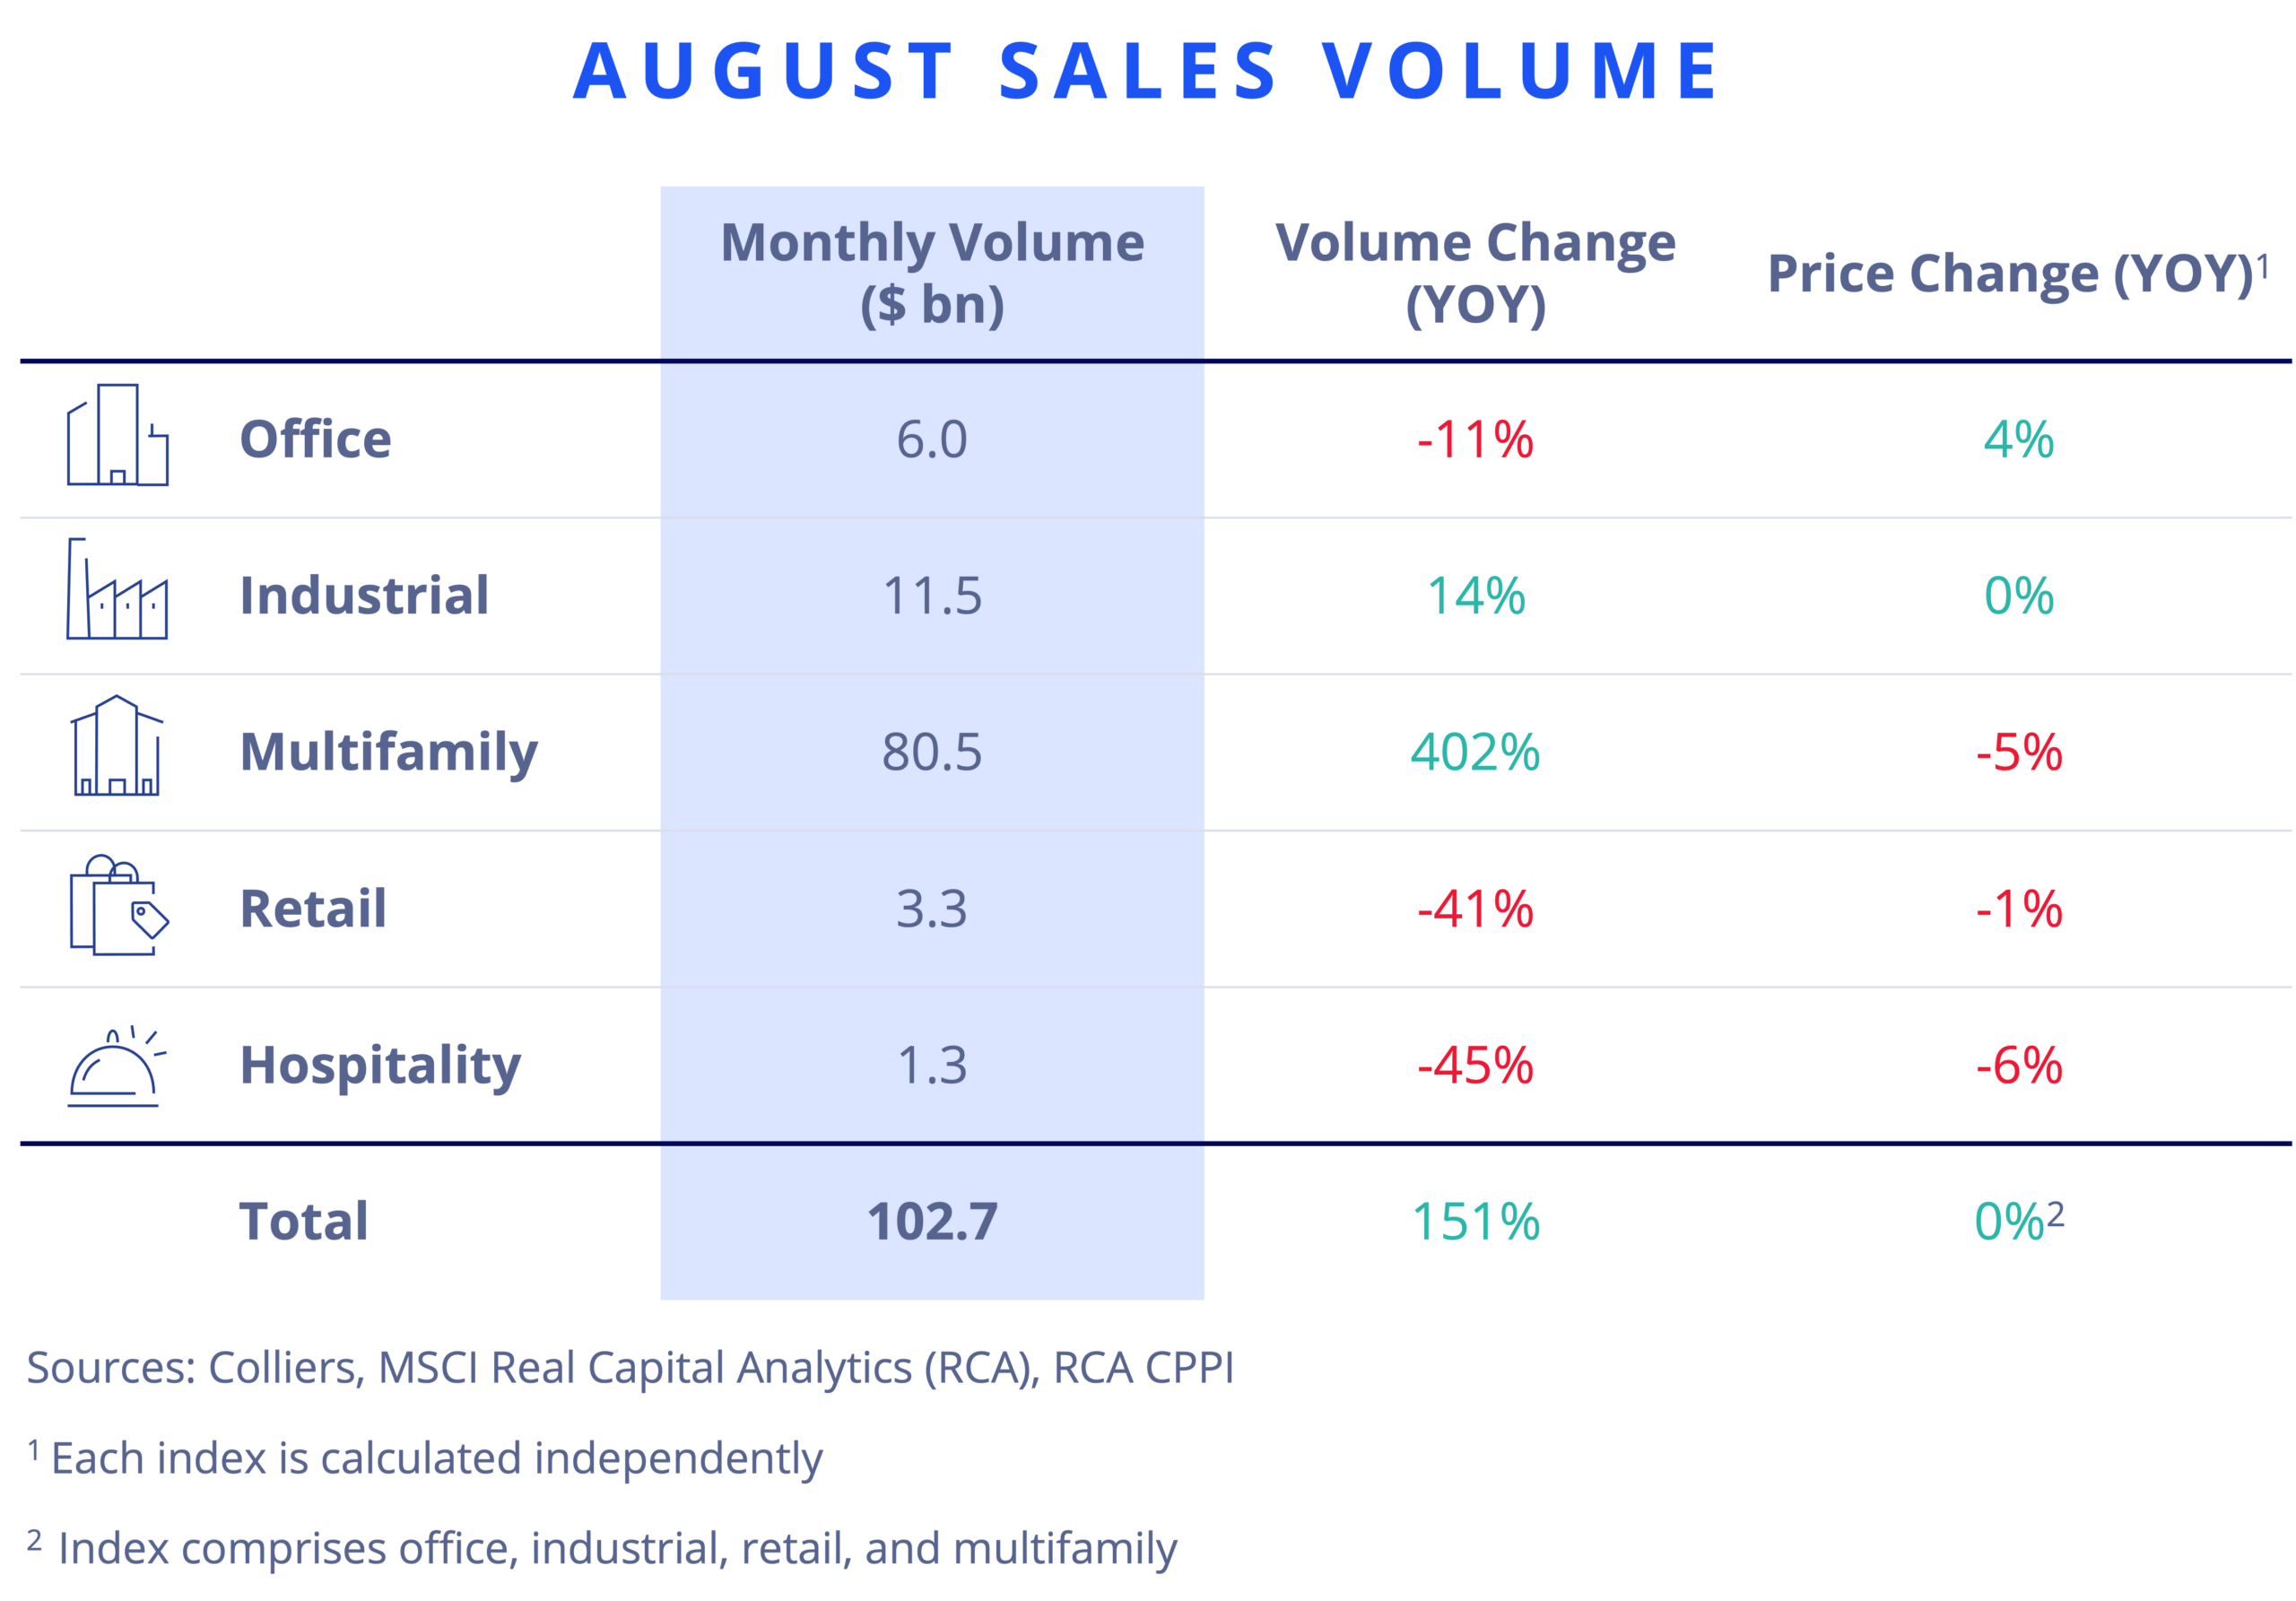
- August deal volume hinged on entity-level transactions. These sales totaled $70 billion, setting a record pace for M&A activity.
- Year-to-date trends show more resilience than August alone. Multifamily and office remain challenged, while industrial, retail, and hotel volumes are outpacing 2025.
- Individual asset sales remain soft. Excluding portfolio and entity deals, declines were seen across multifamily, office, hotel, and retail.
- Volume and pricing moved independently by sector. Office prices rose 4% year over year despite declining volume, while multifamily prices fell despite a surge in August volume.
August’s headline figures masked a bifurcated market. Entity-level transactions inflated overall volume. When stripped of those deals, individual asset sales contracted sharply across most sectors. Meanwhile, retail and industrial showed month-over-month price appreciation on an annualized basis, suggesting that weakness from late 2025 and early 2026 may be beginning to ease.
Office
Office investment fell 11% year over year in August, but activity varied by subtype. CBD volume dropped 37%, while suburban activity rose 5%. Pricing diverged as well: CBD cap rates fell 20 basis points from last year to 7%, while suburban cap rates rose 10 basis points to 7.5%. CBD assets continue to face pandemic-era uncertainty around office utilization, though emerging tenant demand signals suggest that headwind is beginning to ease.
Industrial
Industrial investment climbed 14% year over year in August, bringing year-to-date volume 33% ahead of 2025. Portfolio activity drove the entire gain; excluding portfolios, deal volume fell 17%. No major entity-level deals closed. Pricing stabilized modestly, with industrial property values up just 0.1% year over year, though price growth has accelerated to a 4.5% annualized rate since June.
Multifamily
Multifamily saw a temporary surge in August from the Equity Residential/AvalonBay merger that created Vivmark, but individual deal flow remained weak. Individual asset sales fell 35% year over year, with declines across garden apartments and mid- and high-rise properties. Year-to-date trends remained weak, with individual asset sales running 6% behind the same period in 2025. Pricing deteriorated further, with the apartment RCA Commercial Property Price Index (RCA CPPI) down 4.7% year over year and falling at an 8.2% annualized rate from July, signaling accelerating price pressure.
Retail
Retail investment fell 41% year over year in August, reflecting a choppy 2026 marked by alternating monthly swings. Year-to-date through August, total volume was 4% ahead of 2025, driven by a 13% increase in individual asset sales, despite portfolio and entity-level activity falling 32% and 14%, respectively. The retail RCA CPPI was down 0.5% year over year in August but improved at a 3.5% annualized pace month over month.
Hospitality
Despite a 45% year over year decline in August hotel investment, year-to-date activity is running 27% ahead of 2025. Full-service deal volume is up 65% year-to-date, even after falling 55% for the month. Limited-service sales declined 33% in August and trail last year’s pace by 2% year-to-date. Pricing pressures that peaked in late 2025 and early 2026 have eased. Hotel property values improved at a 9.1% annualized rate month over month.
 Rachael Rothman
Entity-level transactions accounted for $70 billion of August’s $102.7 billion in total deal volume.
 Steig Seaward