- Overall delinquency edged down to 7.85% but remains above both year-ago (7.29%) and six-month (7.14%) levels.
- Office remains the most distressed property type, with delinquency rising to 12.0% as several large assets failed to refinance at maturity.
- Hospitality (+49 bps) and retail (+24 bps) posted the largest monthly increases, reaching 5.84% and 7.2%, respectively.
- Maturity defaults continue to dominate, with non-performing matured balloon loans accounting for 81% of newly delinquent balances.
- The market’s broader distress rate would reach 9.81%, factoring in performing matured balloons, up 19 bps from July.
The CMBS delinquency rate was essentially unchanged in August, slipping one basis point to 7.85%, according to Trepp. However, the underlying story remains one of persistent credit stress rather than improving fundamentals. While several large loans cured during the month, new maturity-related defaults, particularly in the office sector, continued to offset improvement. Non-performing matured balloon loans accounted for 81% of newly delinquent balances, highlighting refinancing risk as the primary driver of credit deterioration.
Office remains the market’s biggest trouble spot. The sector’s delinquency rate increased to 12.0%, the highest among major property types, as several large assets moved directly into non-performing matured balloon status. While a handful of notable cures provided some relief, office continues to face significant refinancing challenges.
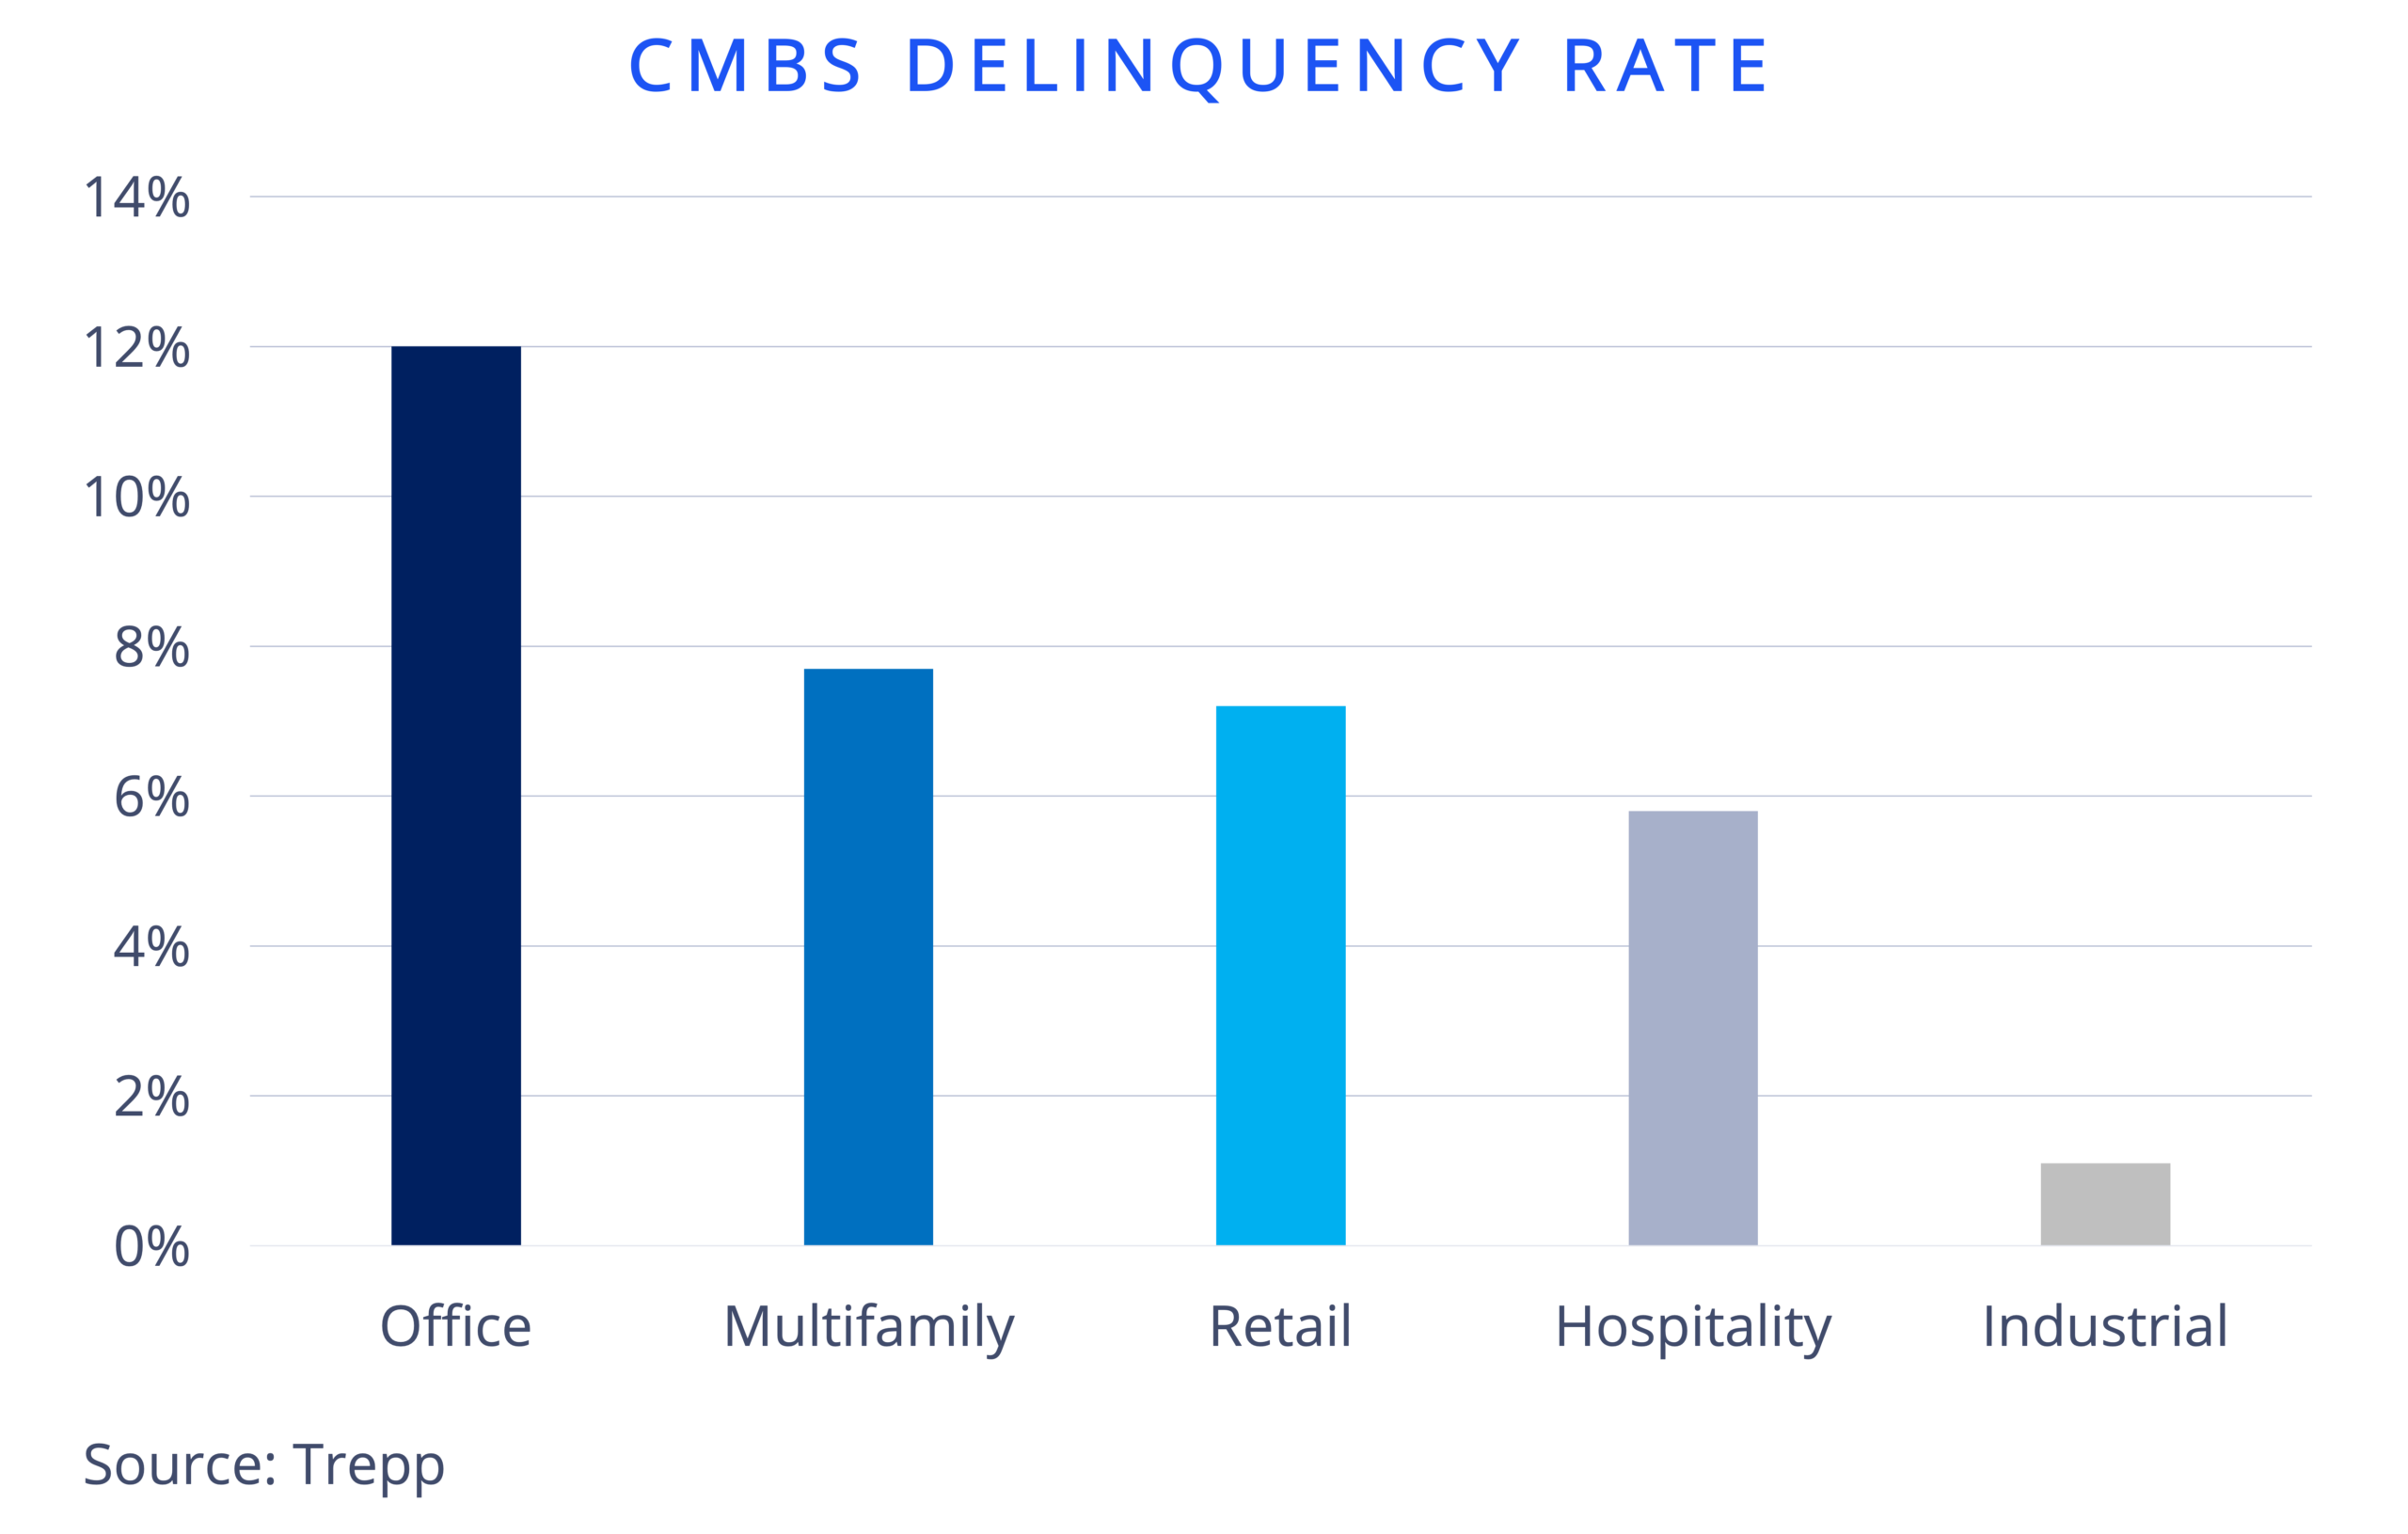
Retail and hospitality also weakened during the month. Hospitality delinquency climbed 49 basis points to 5.84%, while retail rose 24 basis points to 7.2%, helping push the seriously delinquent rate to 7.69%, up 12 basis points from July.
The broader distress picture remains elevated. Including performing matured balloon loans, the CMBS distress rate would reach 9.81%, up 19 basis points month over month, suggesting additional pressure could emerge as more loans reach maturity and refinancing options remain constrained.
 Steig Seaward
Maturity defaults continue to drive credit stress, accounting for most new delinquencies.
 Rachael Rothman