- Corporate bond yields have risen sharply since the Iran conflict began. An index of BBB-rated corporate bonds, the lowest investment-grade rating, averaged a 6.19% yield on Oct. 6, up from 4.90% on Feb. 27, the last trading day before the conflict.
- Most major property types still offer higher cap rates than the BBB bond yield. MSCI’s August cap rates for office, retail, industrial and hospitality all exceeded the BBB bond index’s 6.19% yield as of Oct. 6.
- Higher Treasury yields are driving the increase in bond yields. The gap between BBB and 10-year Treasury yields is essentially unchanged since February, and expected inflation has barely moved.
- Multifamily is the only major property type earning less than BBB bonds. Its 5.67% average cap rate is among the highest since 2017.
As bond yields rise, so do investors’ return expectations for commercial real estate. Higher Treasury yields limit cap rate compression, as Colliers noted in August, while Green Street recently argued that bonds now look more attractive than property. The question is which property types still offer more income than bonds.
Through August, office averaged a 7.66% cap rate, retail 7.16%, industrial 6.94%, and hospitality 8.55%, above the 8.03% average yield on riskier high-yield bonds. Cap rates exclude spending on items such as roofs and tenant improvements, so the income advantage is somewhat smaller than it appears. Still, cap rates are higher than a year ago across every major property type, meaning buyers are paying less for each dollar of income. Office cap rates are at their highest since 2011, and retail since 2013.
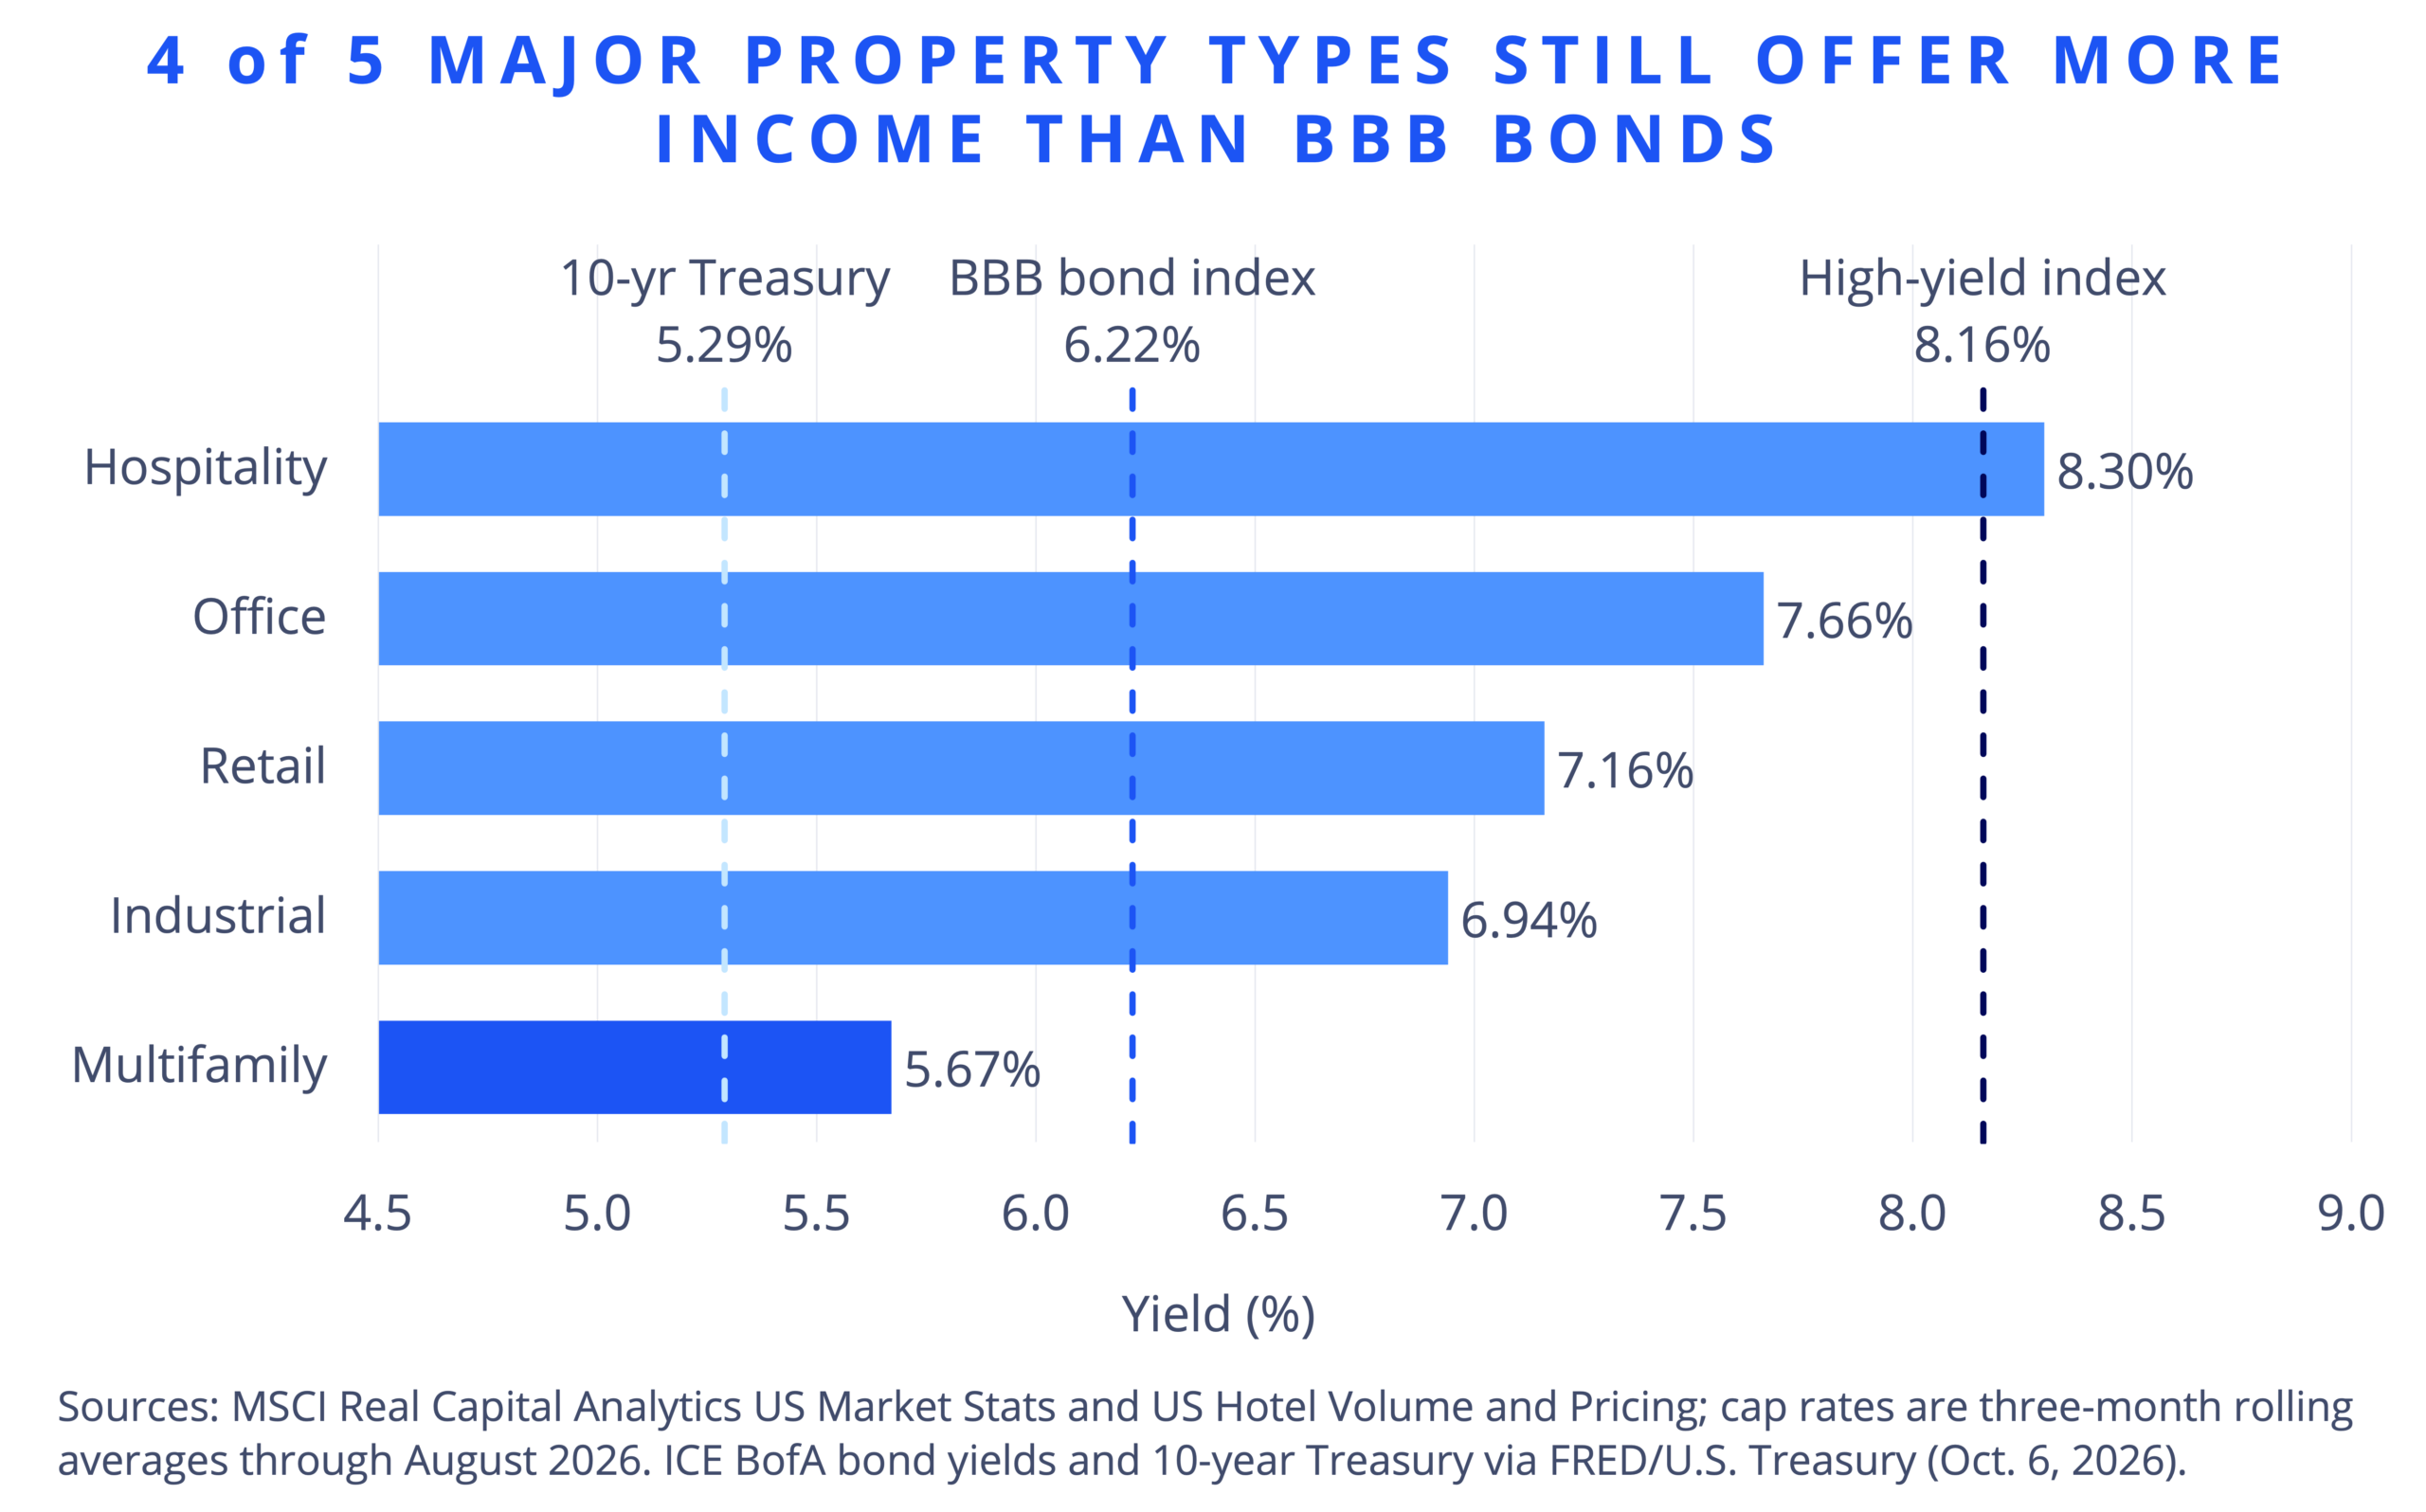
The drivers behind the rise in bond yields are telling. Since the Iran conflict began, the 10-year Treasury yield has risen 1.30 percentage points to 5.27% as of Oct. 6, and the BBB yield has increased by nearly the same amount. That parallel suggests investors are no more concerned about corporate defaults than they were in February. Bond-market measures of expected inflation rose only 0.11 percentage points, indicating inflation expectations played a limited role in the increase. Investors expect the Federal Reserve to keep short-term rates higher, and they are demanding extra yield to lend for longer periods.
Bond interest payments are fixed, while rents can rise over time. That matters for multifamily, where cap rates are below BBB yields today. Multifamily rents in the 50 largest U.S. markets rose 0.9% in the year through June, according to Green Street, roughly enough to cover the 0.52-percentage-point gap between multifamily cap rates and BBB yields.
Timing adds risk. Many August sales were priced before the BBB yield rose another 0.56 percentage points in September. If rates hold near current levels, buyers may look for slightly higher cap rates on industrial and multifamily properties, whose cap rates are closest to the BBB yield.
 Rachael Rothman
If bond yields stay high, industrial and multifamily prices may soften, giving new buyers more income per dollar invested.
 Steig Seaward